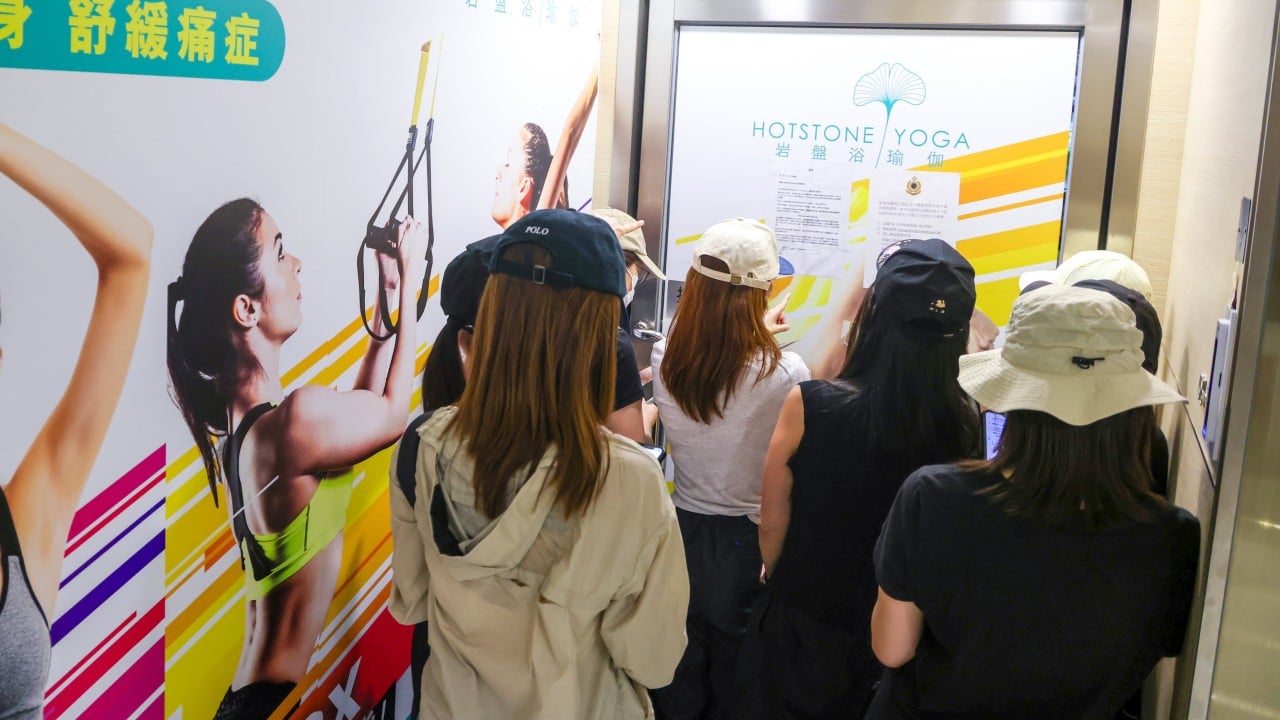
The sudden cessation of operations at Hotstone Yoga, which left hundreds of consumers with millions in unrecoverable prepaid liabilities and triggered immediate intervention by the Consumer Council and Hong Kong Customs, exposes a structural vulnerability embedded within the high-churn prepayment business model. When a multi-branch wellness enterprise collapses overnight, the event is rarely an instantaneous market accident. Instead, it represents the final phase of a predictable financial decay curve where forward-sold liabilities outpace operational cash generation, forcing operators into a terminal liquidity trap.
Examining the mechanics of such failures requires moving past anecdotal accounts of aggressive sales pitches and focusing on the underlying financial architecture. The fitness and wellness sector relies heavily on upfront capital extraction. Consumers purchase multi-month or multi-year packages at a discounted marginal rate per session, providing operators with immediate liquidity. In financial terms, this acts as a zero-interest loan from the consumer to the corporate entity, booked as unearned revenue or deferred income on the balance sheet.
The primary economic flaw in this model lies in the mismatch between liability recognition and cash expenditure. Healthy businesses treat prepaid capital as restricted funds or amortize it strictly as services are rendered. Distressed operators, conversely, frequently utilize deferred revenue from incoming cohorts to subsidize the operational overhead, debt service, or past losses of existing locations. This creates a classic Ponzi-like cash flow dependency: the enterprise requires an ever-increasing volume of new customer acquisition simply to fulfill the contractual obligations of past sales.
When macro-environmental factors or brand erosion slow down new customer acquisition, the cash conversion cycle breaks down instantly. Fixed costs—specifically commercial real estate leases in high-density urban areas, staff salaries, and utility overhead for temperature-controlled environments like hot yoga studios—remain rigid. Variable costs shrink, but not fast enough to offset the sudden cessation of inbound prepaid cash. Management faces a binary choice: inject fresh equity or halt operations before statutory insolvency forces personal liability.
The regulatory response in jurisdictions like Hong Kong typically highlights the enforcement gaps within the Trade Descriptions Ordinance, particularly regarding unfair trade practices and aggressive closing-down sales. Investigations frequently uncover patterns where management aggressively promoted long-term prepaid packages while actively planning or concealing imminent insolvency. In the case of Hotstone Yoga, the escalation from consumer grievances to criminal arrests by law enforcement underscores the transition of the issue from a civil contract dispute to potential fraud. When a director accepts payment for services knowing that the entity cannot legally or operationally deliver them, the transaction crosses the legal threshold into deceptive commercial practices.
This recurring pattern has intensified legislative pressure for structural reforms, most notably the introduction of statutory cooling-off periods and mandatory refund windows for fitness and beauty contracts. From an economic perspective, a mandatory cooling-off period acts as a friction mechanism that alters the cost-benefit matrix for aggressive sellers. By forcing operators to hold a percentage of funds in escrow or allow unconditional cancellation windows, the regulation dismantles the immediate cash-grab capability that underpins high-risk wellness operations. However, industry pushback centers on the liquidity squeeze such rules impose on legitimate operators who rely on upfront capital for initial build-out costs and equipment financing.
To isolate the systemic risk from isolated corporate malfeasance, stakeholders must evaluate the financial health of prepaid service providers through three quantitative indicators:
The Deferred Revenue Velocity Ratio measures the rate at which unearned income is consumed relative to actual capacity utilization. If a studio sells ten thousand sessions but possesses the physical and human resource capacity to deliver only two thousand per month, a hidden liability overhang is accumulating.
The Working Capital Buffer assesses whether prepaid cash is ring-fenced or utilized for operational expenditure. An operator operating on a net-negative working capital cycle—where current liabilities vastly exceed liquid short-term assets—is functionally insolvent long before doors close.
The Customer Acquisition Cost to Lifetime Value spread reveals whether the business model depends on constant volume expansion or sustainable retention. When acquisition costs spike while retention plummets, operators invariably resort to discounting multi-year packages to manufacture artificial liquidity.
Protecting consumer interests and stabilizing the wellness market requires replacing reactionary watchdog interventions with preventative financial transparency. Regulators must mandate independent escrow accounting for prepaid service contracts exceeding specific duration thresholds, ensuring that consumer capital remains tied directly to service delivery rather than general corporate solvency. Until statutory frameworks enforce strict separation between deferred customer funds and operational cash flow, sudden enterprise collapses will remain an inevitable feature of the prepayment economy.


