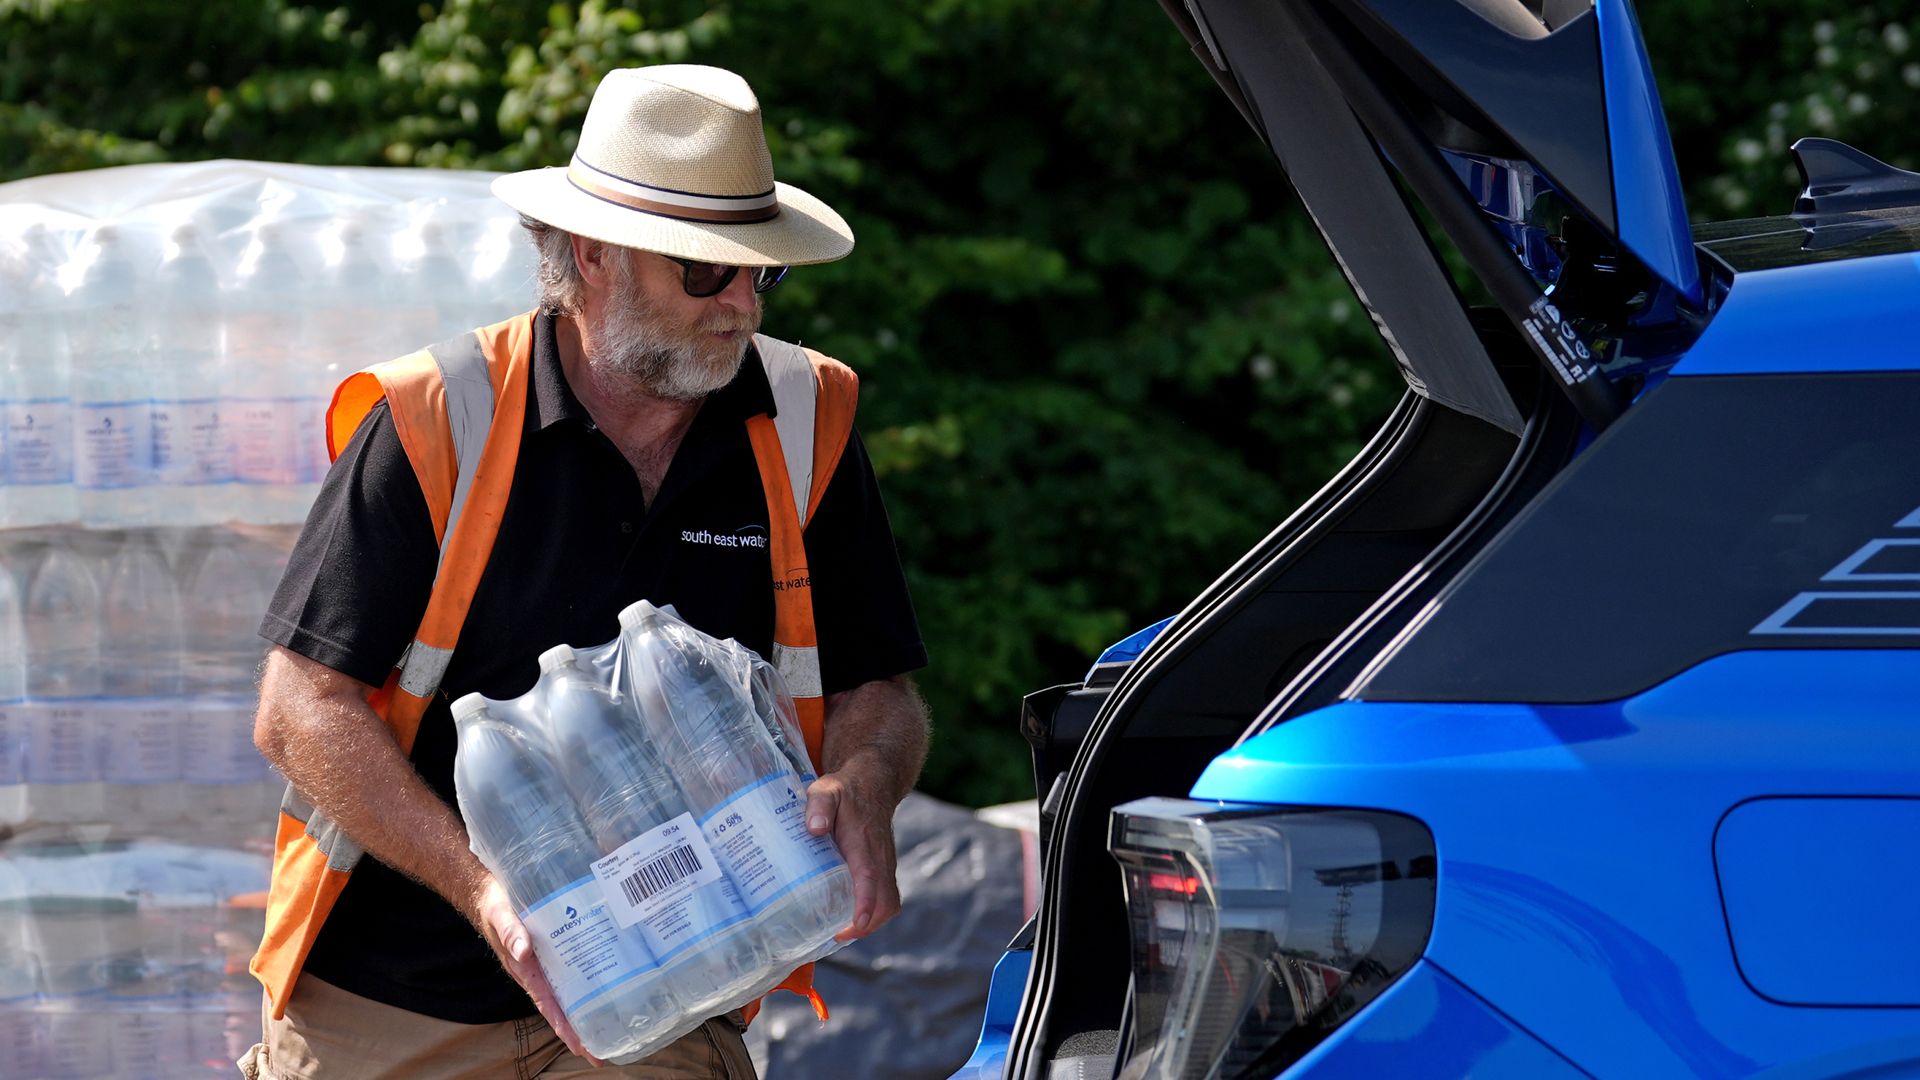
The appointment of an independent monitor to oversee South East Water marks a structural shift in how utility regulation functions under prolonged operational strain. When Ofwat secured a financial redress package coupled with mandated external oversight, it exposed the limits of traditional statutory fines. Punitive monetary adjustments alone fail to alter asset management behavior when regulated entities operate within natural monopolies.
To understand why traditional oversight breaks down, we must examine the economic architecture of water utilities. Regulated utilities function within constrained revenue allowances set during periodic price reviews. When operational resilience degrades—manifesting as supply interruptions, network leakage, and asset fatigue—the standard corporate response often prioritizes short-term cost containment over capital expenditure. This creates an internal conflict of interest between shareholder return and network durability. Read more on a connected subject: this related article.
The introduction of an external monitor introduces an exogenous variable into this closed loop. Grant Thornton’s appointment as the independent monitor shifts the verification burden away from self-reporting. Under Section 19 undertakings, the structural mechanism relies on three distinct operational pillars:
First, real-time verification of asset health replaces retrospective incident accounting. Historically, regulatory intervention occurred post-failure. The monitor's mandate is designed to track leading indicators—such as pumping station redundancy, main burst frequencies, and treatment works capacity—before supply failure manifests for end-users. Additional reporting by Business Insider explores similar views on the subject.
Second, governance decoupling ensures that turnaround execution operates independently of legacy corporate inertia. Utilities under enforcement are required to embed board-level oversight, but internal directors face institutional friction. An independent monitor provides an objective benchmark that bypasses internal reporting filters, reporting directly to the regulator.
Third, cost-allocation mechanics separate regulatory enforcement from consumer bills. The financial burden of the monitor is absorbed by the utility’s shareholders rather than passed through to household customers. This aligns financial accountability with operational failure, ensuring that the cost of regulatory friction punishes equity performance rather than customer tariffs.
The primary limitation of this model lies in execution risk. An independent monitor possesses observational and advisory authority, but lacks executive control. If management teams fail to operationalize the required performance improvement plans, the monitor can only report non-compliance back to the regulator, triggering further escalation rather than immediate operational correction.
The trajectory of South East Water hinges on whether this external oversight mechanism can bridge the gap between financial penalties and physical asset renewal. The success of the intervention will not be measured by the volume of compliance reports generated, but by the measurable reduction in network vulnerability during peak demand cycles.