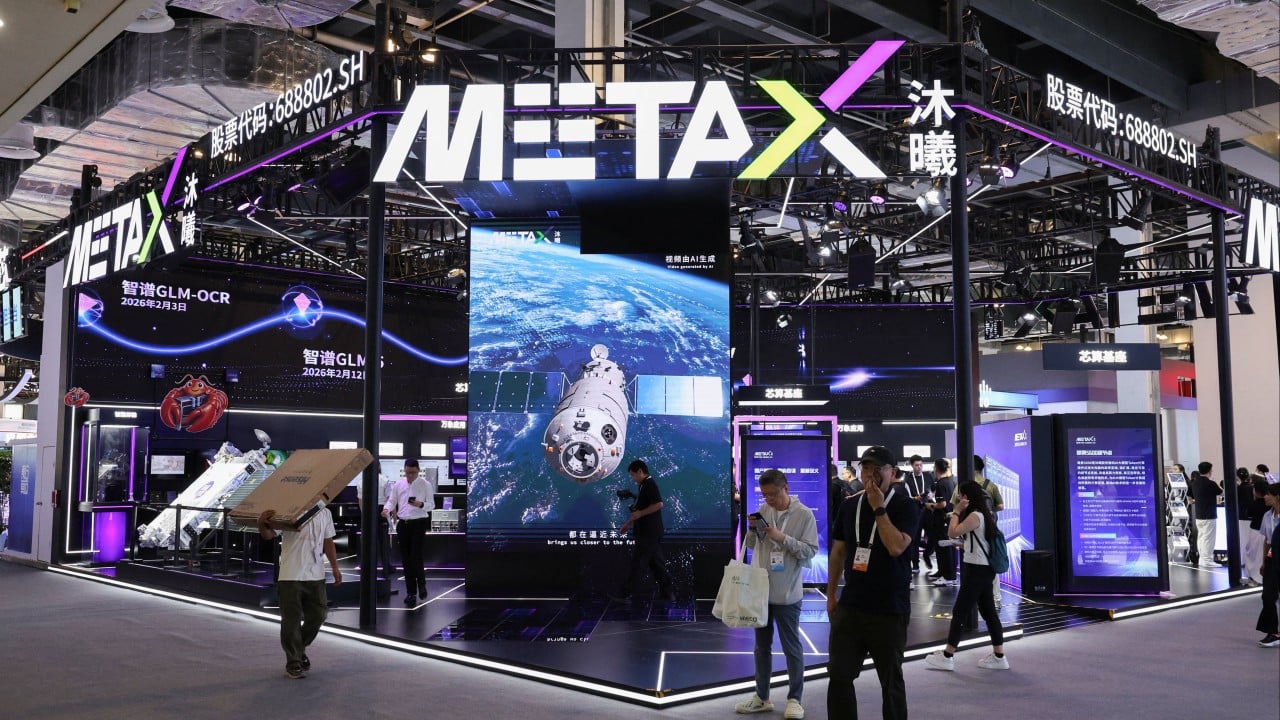
The expiry of initial public offering lock-up periods for Chinese domestic graphics processing unit designers represents a critical stress test for the sovereign computing-power supply chain. When MetaX Integrated Circuits approached the release of approximately fourteen million previously restricted shares—valued near 6.83 billion yuan—market participants confronted a structural liquidity event rather than a simple calendar milestone. This transition from artificial scarcity to expanded free float strips away the valuation cushions provided by post-debut trading lock-ups, exposing underlying financial fundamentals to direct market pricing.
The Mechanics of Supply Expansion
Initial public offering structures in mainland China's STAR Market create a distinct pricing dynamic. Early-stage institutional investors and venture capital backers routinely enter positions at fractions of the offering price, securing paper returns exceeding three hundred percent even amid severe secondary market corrections. Consequently, the removal of trading restrictions establishes an immediate structural incentive for capital realization.
The market sensitivity surrounding MetaX stems directly from precedent. When peer designer Moore Threads experienced its initial lock-up expiration, secondary market valuations plummeted by twenty percent within sessions, triggering a broader contagion effect across domestic semiconductor equities. This vulnerability arises because the free float of these firms expands rapidly—in MetaX's case, by roughly seventy-five percent—without a proportional shift in underlying addressable demand or manufacturing capacity.
Revenue Realization Versus Cash Flow Strain
A superficial reading of corporate income statements suggests a sector undergoing an unchecked golden age. Driven by stringent United States export controls and aggressive state-backed self-reliance directives, domestic semiconductor manufacturers have captured guaranteed market share inside domestic data centers and cloud providers. MetaX posted first-half revenues exceeding 1.3 billion yuan, accompanied by a net profit attribution of 612 million yuan that marked a headline-grabbing turnaround from prior-year losses.
A rigorous structural audit, however, reveals significant divergence between accounting net income and operational cash generation:
- Non-GAAP Adjustments: Excluding non-recurring gains and one-time accounting adjustments, core operations frequently remain unprofitable during periods of rapid scaling.
- Capital Intensity: Research and development expenditures consistently consume between thirty-five and forty percent of total revenues, driven by the immense engineering overhead required to tape out advanced 7-nanometer architectures and integrate high-bandwidth memory variants.
- Working Capital Burn: Operating cash flow profiles remain heavily negative, driven by prolonged accounts receivable cycles from state-affiliated enterprise clients and upfront wafer fabrication commitments at domestic foundries.
These metrics confirm that while policy tailwinds and procurement mandates guarantee top-line growth, the operational cash conversion cycle remains deeply constrained.
The Geopolitical Moat and Margin Pressure
The valuation multiples commanded by domestic hardware designers rely on the assumption of a protected domestic market. Because export restrictions prevent hyperscalers like Alibaba, Tencent, and Baidu from acquiring bleeding-edge foreign accelerators, state-endorsed alternatives capture captive demand. Government procurement lists formally designate certified hardware from approved domestic vendors, cementing a baseline revenue floor.
Yet, this protected environment introduces structural margin compression. Domestic foundries operating under severe lithography restrictions face lower yields and higher per-wafer costs compared to global peers. As a result, unit economics for chips like the C600 series feature compressed gross margins. Designing around supply chain bottlenecks requires expensive architectural workarounds, inflating fixed overheads before volume efficiencies can materialize.
Portfolio Allocation Under Volatility Regimes
For institutional allocators, the transition of semiconductor equities from speculative policy plays to mature growth assets requires a strict operational focus. Equity valuations can no longer rely on macro-level enthusiasm for technological independence. Portfolio construction must account for three distinct risk vectors:
- Free Float Absorption Capacity: Assessing whether secondary market liquidity can absorb institutional block sales without triggering cascading technical sell-offs.
- R&D Efficiency Ratios: Tracking the ratio of revenue growth to sustained research expenditure to identify firms capable of transitioning from subsidized development to organic profitability.
- Foundry Access Continuity: Monitoring foundry allocation agreements and advanced packaging availability, which represent the ultimate physical ceiling on hardware delivery schedules.
The medium-term trajectory of domestic semiconductor equities depends less on quarterly headline profits and more on the ability of designers to convert state-mandated demand into positive free cash flow before early investor liquidity events completely reset valuation multiples.