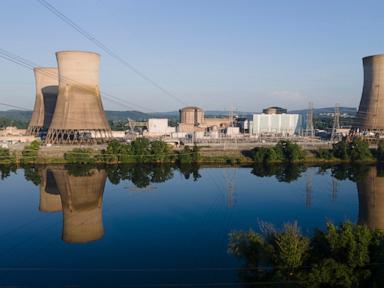
Ribbon-cuttings in South Indian data infrastructure are loud. Subsea cables are dramatic. Political photo-ops look great on investor decks.
None of that pays the power bill.
Every time a high-profile data centre launches in Chennai—especially one backed by Singaporean capital and blessed by regional politicians—the coverage follows the exact same script. Boom. Digital gateway. AI hub. Billions flowing into southern India. You read the headlines and think server racks sprout out of monsoon puddles like mushrooms.
They do not. Building a facility is the easy part. Keeping it cool, fed, connected, and profitable for fifteen years without choking on grid realities or water scarcity is where real operators earn their stripes—or quietly bleed margin.
The Lazy Consensus Around Chennai Data Centres
The lazy consensus goes like this: India has massive digital demand, subsea cables land in Chennai, Singapore operators bring institutional discipline, state governments roll out red carpets, and therefore every new data centre in the city is an automatic win.
That sounds neat. It is also lazy.
Data centre infrastructure is not a software product you ship once and watch scale with zero marginal cost. It is heavy industrial real estate glued to municipal grids, local water tables, high-voltage substations, and fiber routes that have single points of failure people like to pretend do not exist. A shiny launch ceremony tells you capital arrived. It tells you almost nothing about unit economics once the cameras pack up.
I have watched operators pour tens of millions of dollars into regional buildouts because the macro story looked irresistible on paper, only to run straight into transformer lead times, utility tariff friction, and customer acquisition cycles that move at glacial speed. Macro demand is a tailwind, not a guaranteed yield.
Define the Real Game Before Cheering the Launch
To talk straight about a data centre—whether it belongs to CapitaLand or any other major operator—you have to separate three things people routinely mash together: capacity, utilization, and yield.
- Capacity is the physical shell and power envelope—megawatts of IT load and square footage. Anyone with enough capital and patience can build capacity.
- Utilization is how much of that power envelope paying workloads actually consume over time. Empty halls with gleaming chillers burn cash.
- Yield is the net financial return after power costs, cooling overhead, debt service, maintenance capex, and customer churn.
Most press coverage treats capacity announcements like completed cash flows. In reality, a newly unveiled data centre is a capital commitment sitting on a clock. Every month between energizing the substation and signing sticky, creditworthy enterprise or hyperscale tenants is a drag on return.
When Singaporean capital meets Tamil Nadu policy ambition, the strategic logic is clear on the surface. Singapore is land-constrained and power-tight; cross-border expansion makes sense. Chennai offers subsea cable landings connecting South Asia to Southeast Asia and beyond, alongside a deep technical talent pool and active industrial policy.
None of those advantages erase physics or finance. Heat still has to go somewhere. Kilowatt-hours still cost money. Enterprise buyers still care about latency, redundancy, and contract terms more than celebratory slogans.
Why "Gateway" Status Is Often Overread
People love calling coastal cities "gateways." It sounds grand. It implies traffic simply pours through the front door and lands in your racks.
Network engineering does not care about poetic labels. Traffic follows routing economics, peering depth, latency budgets, and application architecture. Landing a subsea cable near a city is a strong foundation, not an automatic monopoly on regional traffic. Backhaul corridors, metro fiber diversity, IXP presence, and cloud on-ramps determine where packets actually settle.
Enterprise workloads are even pickier. Banks, manufacturers, SaaS firms, and AI builders do not move mission-critical infrastructure because a ribbon got cut. They move when availability SLAs are proven, compliance boxes are checked, network paths are resilient, and pricing beats staying put or using an existing hub.
A ribbon-cutting marks the end of construction hype and the start of the hardest operational test in infrastructure: turning fixed megawatts into recurring, high-margin cash flow.
The Questions People Should Actually Ask
When news breaks about a major data centre project in Chennai, standard search queries circle around predictable questions: Why is Chennai a major data centre hub? How do Singapore operators expand in India? What role does state leadership play in attracting tech infrastructure?
Those questions are not useless, but they stop right before the parts that separate winners from laggards.
"Why is Chennai a major data centre hub?"
That framing treats Chennai's position as settled destiny rather than a competitive arena with real constraints. Chennai has real strengths—subsea connectivity, industrial depth in Tamil Nadu, and a growing tech ecosystem. Yet Mumbai and Hyderabad are fierce competitors with massive scale, deep enterprise roots, and aggressive expansion of their own.
Calling a city a "hub" also hides local bottlenecks. Power reliability, peak summer heat, cooling water availability, and right-of-way headaches for fiber and high-voltage lines test operators every single day. A location can have strong macro appeal and still punish sloppy execution at the site level.
"How do cross-border operators win in a market like India?"
If you think bringing foreign capital and a respected brand name is enough, you have not spent enough time watching international expansions stall. Local execution decides outcomes. Permitting nuances, utility coordination, vendor management, and local talent retention matter far more than headquarters prestige.
In my experience, the operators that hold up best are disciplined about phased buildouts. Instead of betting the farm on day-one occupancy, they size initial capacity to real demand commitments, design for modular expansion, and guard balance-sheet discipline when timelines slip.
"What does government backing actually change?"
Political support can speed up approvals, clarify policy incentives, and signal industrial priority. That helps—especially in capital-heavy infrastructure where red tape can turn a two-year project into a five-year slog.
Still, governments do not sign commercial leases or fix an overloaded feeder line. Policy opens doors; commercial demand and engineering rigor keep the lights on.
Imagine a Scenario Where Everything Looks Great on Paper
Imagine a scenario where a premier operator unveils a flagship data centre in Chennai with fanfare from both Singapore and Tamil Nadu leaders. On launch day, every box looks ticked: prime connectivity story, strong institutional backing, supportive state leadership, and ambitious capacity targets.
Now fast-forward twenty-four months. Power costs run slightly hotter than modeled during peak summer months. Cooling efficiency takes extra tuning to hit target power usage effectiveness without risking thermal trips. Several prospective tenants delay migrations because their internal application refactoring takes longer than planned, while hyperscalers negotiate hard on pricing for multi-megawatt blocks.
Nothing catastrophic happens. There is no scandal. Yet equity returns look noticeably tighter than the launch-day press release implied. That gap between headline excitement and ground-level grind is where real infrastructure analysis lives.
What Heavy Hitters in Infrastructure Actually Watch
Ask veteran data centre executives, infrastructure fund managers, or grid engineers what keeps them up at night, and they rarely talk about slogans. They talk about power availability, grid interconnection, cooling water, supply chain lead times, and credit quality of tenants.
Industry leaders such as Equinix, Digital Realty, NTT Global Data Centers, and Nxtra by Airtel have built massive footprints across Asia by treating infrastructure as a relentless operational craft. Whether a facility sits in Singapore, Tokyo, Mumbai, or Chennai, long-term winners obsess over uptime engineering, energy efficiency, interconnection density, and disciplined capital allocation.
Even top-tier operators face trade-offs. Pushing for rapid scale can compress margins if supply arrives ahead of demand; holding back too much can cost land or power allocations in tight markets. Every strategy carries friction.
The Honest Downside of Looking at This Cynically
A contrarian lens has a blind spot if you let it turn into pure cynicism. Skepticism is useful. Reflexive pessimism is lazy too.
South Asia's digital and cloud footprint is genuinely expanding. Enterprises are modernizing legacy stacks, AI inference and localized data requirements are growing, and regional connectivity continues to deepen. Operators that enter early, secure scarce power and land, and build strong local relationships can capture real long-term value that latecomers struggle to match.
If you dismiss every new project as hype, you miss legitimate compounding assets. If you swallow every launch announcement whole, you confuse promises with profits.
Actionable Rules for Anyone Evaluating Data Centre Moves
If you are an investor, enterprise buyer, engineer, or policy watcher looking at data centre expansion in Chennai or anywhere else in Asia, skip the confetti and run a tougher checklist:
- Track energized power, not just announcements. Ask when high-voltage power is actually delivered to the site and what redundancy tier is truly built—not merely promised on a slide.
- Look past anchor hype to contract duration and credit quality. Long-term commitments from creditworthy tenants beat vanity logos every time.
- Inspect cooling and water math early. High ambient temperatures make thermal management expensive; check how cooling is engineered and sourced before assuming low operating costs.
- Verify network diversity on the ground. Do not assume "near a cable landing" equals low-latency, resilient routing to the exact users and clouds your workloads need.
- Judge management by capital discipline over five to ten years. Data centres are multi-decade assets; patience, balance-sheet strength, and operational boringness win over flash.
A grand opening is just day zero. Judge the building five years later by its uptime, its power bill, and who actually pays to fill it.